How to Create a Cryptocurrency: Coins, Tokens & Costs
Creating a cryptocurrency is three different projects wearing the same name. This guide separates them: a token on an existing chain, your own appchain, or a no-code launcher. With a working ERC-20, the 2026 rulebook in the EU and the US, and a costed model of each route.

Creating a cryptocurrency means one of two things at the engineering level: deploying a token contract onto a blockchain that already exists, or launching a new blockchain whose native asset is your coin. The first is a few hundred lines of Solidity and a few weeks of everything that isn't Solidity. The second is a distributed system with a payroll attached. Nearly everyone who asks how to create a cryptocurrency wants the first one and hasn't yet been told there's a difference.
This guide separates the routes, prices them, and walks the parts most tutorials skip. We build blockchain products for a living, so the goal isn't to talk you into launching a token. It's to make sure you know which of the three projects you signed up for, and what changed in 2026 in Brussels and Washington.
The short version
- A coin is the native asset of its own chain. A token is a contract on somebody else's chain. Still deciding? You want a token.
- Three routes exist: a token on an existing chain (days of code, weeks of everything else), your own appchain or rollup (months), or a no-code launcher (minutes, and no product).
- The contract is the cheap part. An OpenZeppelin ERC-20 with a fixed supply is nine lines.
- Network fees stopped mattering. Ethereum averaged 0.145 gwei with ETH at $2,468 on 10 September 2026 (Etherscan), so deployment costs less than lunch.
- The audit and the liquidity are the two real line items. Sherlock's 2026 market reference puts a simple token audit at $5,000 to $20,000 and a mid-complexity protocol at $40,000 to $100,000.
- The legal ground moved twice in the last two years. MiCA's Title II has applied across the EU since 30 December 2024, and the SEC withdrew its 2019 digital-asset framework on 17 March 2026 and replaced it with a token taxonomy.
- Liquidity is capital, not a fee. Against a $100,000 pool, a $10,000 buy fills about 17% worse than the quoted price. Against $1,000,000, about 2%.
Coin or token: the decision that sets your budget
A coin is the native asset of a blockchain and a token is a smart contract deployed onto one. That single distinction decides your headcount, your timeline and your risk surface, which is why it belongs before every other question.
It comes down to security. Deploy a token on Ethereum, Solana or an established L2 and you're renting a security budget other people pay for. Validators, consensus, client diversity, incident response: none of it is your problem, and none of it appears on your invoice. Launch your own chain and all of it becomes yours permanently. A chain with a thin validator set isn't decentralized in any meaningful sense, and recruiting real, independent validators is a chicken-and-egg problem that no amount of engineering solves.
One opinion saves founders more money than any other advice in this guide: if you have to ask which one you need, you need a token. Most pitches that begin with "we need our own chain" are describing a token with a narrative wrapped around it. Start with a token, prove the demand, and revisit the chain question when block space is genuinely the constraint. Our comparison of custom versus ready-made blockchain platforms walks that trade-off in more depth.
Minting a cryptocurrency is a weekend project. Making one people will hold with real money is the rest of the work, and that part decides whether you have a currency or a curiosity.
Route 1: create a token on an existing chain
Almost every real cryptocurrency launch takes this route. You choose a host chain, write a contract against its token standard, test it, audit it, deploy it, and seed a market so it can be traded.
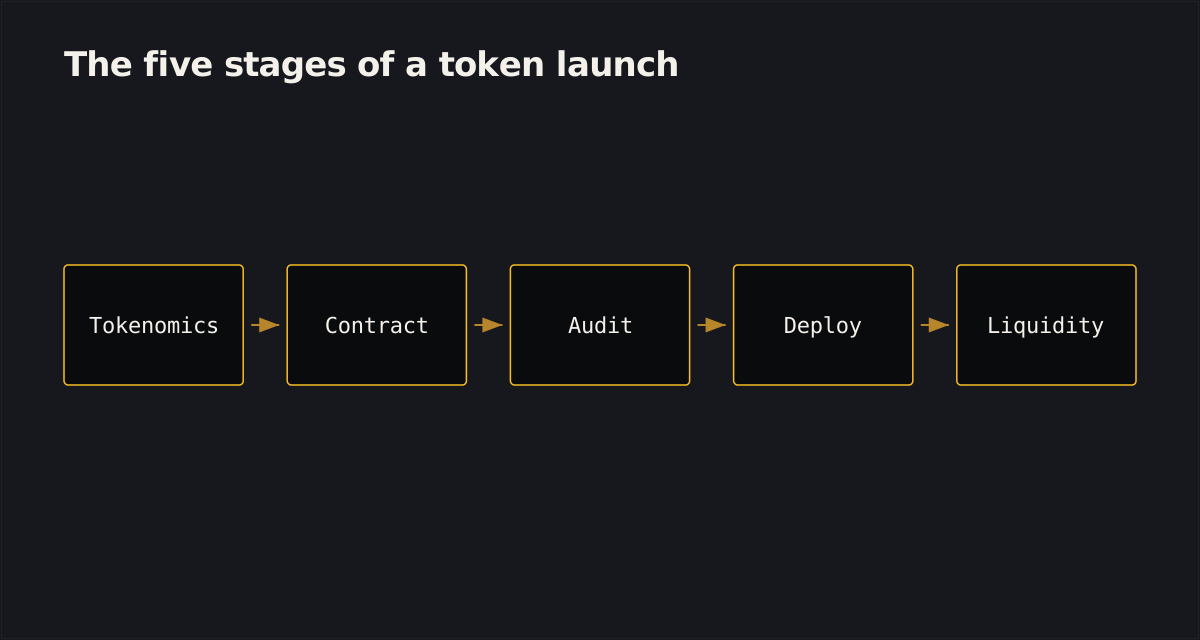
Five stages, in the order they bind:
- Fix the tokenomics before the code. Total supply, decimals, who receives what, and on what schedule. Every one of these becomes a constructor argument or a contract constant, and most of them are permanent. Designing the economics after the contract is written means rewriting the contract.
- Pick the chain and the standard. ERC-20 on Ethereum and every EVM L2, SPL or Token-2022 on Solana, BEP-20 on BNB Chain. The standard is rarely the interesting decision. Where your users, your liquidity and your integrations already live usually is.
- Write and test the contract. Use a reviewed base library rather than hand-rolling transfer logic. Then write the tests for the things a library cannot know: your vesting cliff, your mint authority, your pause conditions.
- Audit, then remediate. A deployed contract is normally immutable, so a shipped bug is a permanent bug. This is the stage that sets your calendar, not your code.
- Deploy and seed liquidity. A token nobody can trade is a spreadsheet entry. Liquidity is covered further down, because it's the line item founders consistently under-budget.
Stages one and five are where projects die. Stage three is the one everybody writes tutorials about.
The contract: a minimal ERC-20 that actually compiles
A fixed-supply ERC-20 is nine lines of Solidity on top of a reviewed library. Here's the current minimal example from the OpenZeppelin Contracts 5.x documentation, which requires Solidity 0.8.20 or later:
Read what it does and, more usefully, what it doesn't. The constructor mints the entire supply to whoever deploys it and then no further minting is possible, because no mint function is exposed. There is no owner, no pause switch, no blocklist and no upgrade path. For a genuinely fixed-supply token that's the correct design, and the plainness is a feature: an auditor reads it in a minute and there's nowhere for anything to hide.
Add a mint function, an Ownable role, a fee-on-transfer hook or a proxy for upgradeability, and you've added something that can be abused and something you'll have to explain. Each is sometimes the right call. None of them is free. The version of this contract that ships is usually this one plus two or three deliberate additions, each of which you can justify out loud to an auditor and to a listing desk.
One detail people miss: initialSupply is denominated in the smallest unit. ERC-20 stores 18 decimals by default, so a supply of one million tokens is 1_000_000 * 10**18, not 1_000_000. Getting that wrong is the most common launch-day mistake we see, and it isn't recoverable on an immutable contract.
Route 2: create a coin by launching your own chain
Launching your own chain means you own consensus, and in 2026 there are two very different ways to do that. Both are real. Only one of them is what most people picture.
Rollups and appchains that settle to an existing L1. The OP Stack describes itself as the shared, open-source stack "that powers Optimism and makes it easy to spin up your own production-ready Layer 2 blockchain." Arbitrum's chain documentation makes the same offer from the other side, giving you "flexibility and control without the constraint of running your own Layer 1 blockchain," with a choice of rollup, AnyTrust or external data availability. You get your own block space and your own gas token, and you inherit Ethereum's settlement guarantees instead of buying your own.
Sovereign application-specific chains. The Cosmos SDK is "a modular, open-source framework for building secure, high-performance distributed ledgers and blockchains," paired with the CometBFT consensus engine. Here you really do run your own validator set and your own security. The clearest production example is dYdX: its documentation describes the protocol as "an L1 blockchain built on top of CometBFT and using CosmosSDK," with validators holding the orderbook in memory off-chain rather than committing it to consensus. That is a chain built because the product needed an execution model no general-purpose chain offers, which is the only good reason to build one.
Code volume isn't the honest comparison. What happens on a Tuesday in month fourteen is. A token contract needs nothing from you: it's immutable and it runs. A chain needs an on-call rota, a client upgrade path, a bridge to defend, an explorer and RPC endpoints to keep alive, and validators who need reasons to stay. Budget the operating cost before the build cost, because the operating cost is the one that never ends.
Route 3: no-code ways to create a cryptocurrency
Token factories and meme launchers create a cryptocurrency on your behalf from a fixed template and hand you a contract address in under a minute. They work exactly as advertised, and the volume they have produced is measurable.
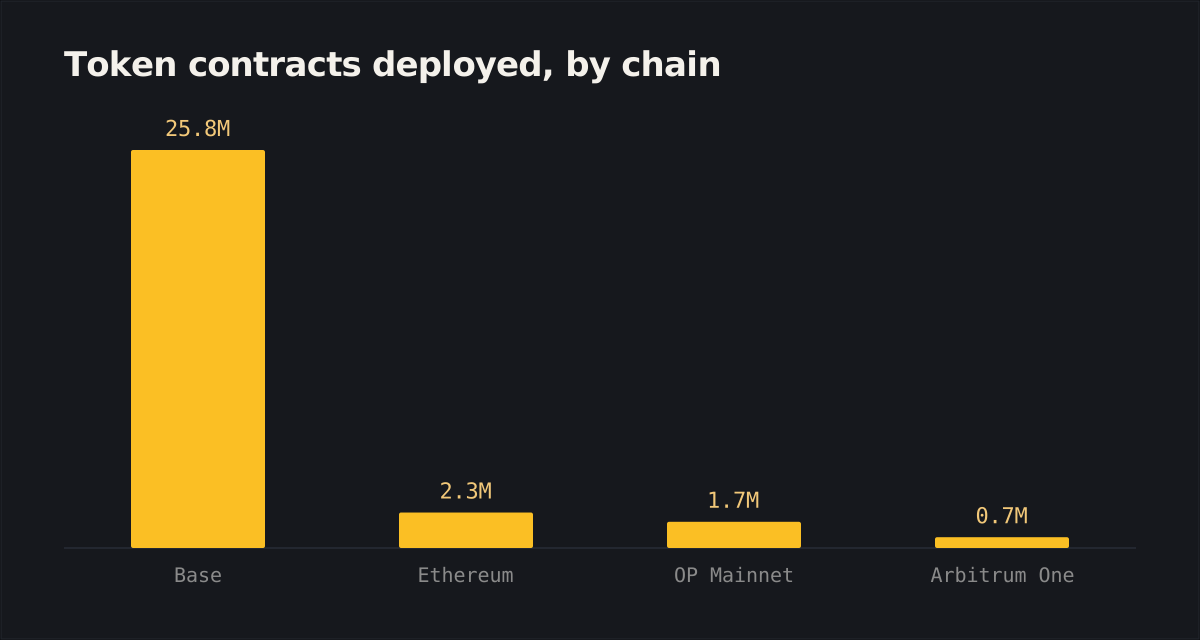
Base carries 25.8 million token contracts against Ethereum's 2.3 million, on a much younger chain (Basescan, Etherscan, captured 10 September 2026). That gap measures friction, not adoption. When deployment costs nothing and a launcher removes the last manual step, the count runs away from you. Read the number for what it is: an explorer counting deployed contracts, where a token with one holder and no market looks exactly like USDC.
Use a launcher when you want to see the mechanics work, or when the token genuinely is a joke and everyone involved knows it. Don't use one when the token has to do a job. In practice you end up with a contract you didn't write, can't modify and can't explain: no test suite to hand an auditor, no ability to add the vesting your investors asked for, and no answer when a listing desk or a regulator asks who controls the mint authority. The route that looks like a shortcut removes precisely the artifacts you need later.
Tokenomics: the part that decides whether the token survives
Tokenomics is the supply schedule, the distribution and the reason anyone would hold your cryptocurrency, and it's the only part of a token launch that can't be fixed after deployment. Four decisions carry almost all of the weight.
Supply. Fixed, capped-with-minting, or inflationary. Fixed is the easiest to explain and the hardest to get wrong. Anything else means somebody holds a mint authority, and that somebody is now a risk your holders have to price.
Distribution. Who gets tokens at genesis and in what proportion: team, investors, treasury, community, liquidity. Publish the actual numbers with the addresses. A distribution that isn't public is assumed to be bad, and the assumption is usually right.
Vesting. Cliffs and linear release schedules enforced by a contract, not by a promise. A team allocation with no on-chain lock is the first thing an experienced buyer checks, and its absence reads as an answer rather than an oversight.
Utility. What the token is for beyond going up. Governance rights, fee discounts, access, staking, collateral: pick one that survives the question "would anyone hold this if the price were flat?" That question is where most token designs come apart.
We will go deeper on supply curves and release schedules in a dedicated guide to tokenomics. The compressed version: write the distribution table before you write the constructor, because the constructor is where it becomes permanent.
The legal reality of creating a cryptocurrency in 2026
Creating a cryptocurrency is now a regulated act in both of the markets that matter, and both rewrote their rulebook in the last two years. Most guides on this topic are still describing 2021. This section is general information and not legal advice; anyone raising money against a token needs a securities lawyer in each jurisdiction they touch.
MiCA: the EU now has a filing, not a grey zone
In the European Union, Regulation (EU) 2023/1114, known as MiCA, has applied since 30 December 2024 under Article 149, with Titles III and IV for asset-referenced and e-money tokens having applied since 30 June 2024. For an ordinary token that is neither of those, Article 4(1) is the operative rule: you may not offer it to the public in the Union unless you are a legal person and you have drawn up a crypto-asset white paper under Article 6, notified it under Article 8, published it under Article 9, and complied with the marketing rules in Article 7.
Article 6 specifies what goes in that white paper, and it is a real document rather than a marketing deck. It covers the offeror, the issuer, the project, the offer, the token, the rights attached to it, the underlying technology, the risks, and the principal adverse climate impacts of the consensus mechanism used to issue it. It must carry a prominent first-page statement that no competent authority has approved it, and it must not make any assertion about the token's future value.
Exemptions are narrower than founders hope. Under Article 4(2), the white paper obligations fall away for an offer to fewer than 150 persons per Member State, for an offer whose total consideration stays under EUR 1,000,000 over a rolling 12 months, or for an offer restricted to qualified investors. Under Article 4(3), Title II does not apply at all where the token is given away free, is created automatically as a reward for validating transactions, is a utility token for a good or service that already exists, or works only within a limited merchant network. Article 4(4) closes the obvious loophole: none of those exemptions survive if you have publicly signaled an intention to seek admission to trading.
One transitional date is worth knowing because it has already passed. Article 143(3) let crypto-asset service providers that were operating lawfully before 30 December 2024 keep going until 1 July 2026 or until their authorization was decided, whichever came first. That grace period is over, which changes who will list your token and how much diligence they run before they do.
The United States: what makes a new cryptocurrency a security
On 17 March 2026 the SEC withdrew its 2019 "Framework for 'Investment Contract' Analysis of Digital Assets" and superseded it with an interpretation titled Application of the Federal Securities Laws to Certain Types of Crypto Assets and Certain Transactions Involving Crypto Assets, Release Nos. 33-11412 and 34-105020. The old framework page on sec.gov now carries the withdrawal notice in its title.
That interpretation sorts crypto assets into five buckets, set out in the Commission's fact sheet. Digital commodities, digital collectibles and digital tools are not securities. Payment stablecoins issued by a permitted issuer under the GENIUS Act are not securities. Digital securities, meaning financial instruments already inside the definition of "security" that happen to be recorded on a crypto network, are. The CFTC joined the interpretation to confirm it will administer the Commodity Exchange Act consistently, and that non-security crypto assets can meet the definition of "commodity."
If you're creating a token, the second half of that document matters most. A non-security crypto asset becomes subject to an investment contract when an issuer offers it "by inducing an investment of money in a common enterprise with representations or promises to undertake essential managerial efforts from which a purchaser would reasonably expect to derive profits." The token isn't the security. The promise wrapped around it is. The same fact sheet states that protocol mining, protocol staking and the wrapping of a non-security crypto asset do not involve the offer and sale of a security, and that certain airdrops do not involve an investment of money under Howey at all.
Read practically: in the United States your marketing copy is now the regulated surface. Two identical contracts, one sold with a roadmap of promised effort and one distributed without any, land in different places. On 18 August 2026 the Commission went further and proposed "Regulation Crypto Assets", with a startup exemption for offerings up to $5 million over four years and a fundraising exemption up to $75 million a year, both carrying tailored disclosure. That's a proposal open for comment rather than law, so you can't plan around it yet.
That distinction holds almost everywhere: issuing a token and mining a coin are treated differently, because issuance has an issuer to hold responsible and validator rewards do not. MiCA Article 4(3)(b) and the SEC's protocol-mining position both land in the same place from opposite directions.
How much does it cost to create a cryptocurrency
The cost to create a cryptocurrency runs from almost nothing to a few hundred thousand dollars, and the spread is set by which route you take and whether you pay for a real audit, not by the act of minting.
Start with what stopped being expensive. Ethereum's average gas price was 0.145 gwei on 10 September 2026 with ETH at $2,468, and Etherscan's own gas tracker priced a token swap at about 12 cents at those levels. Deploying a contract costs more gas than a swap, but at these prices the on-chain fee rounds to nothing on a budget sheet. On an L2 it disappears entirely. Anyone quoting you a large number "for deployment" is quoting you for something else.
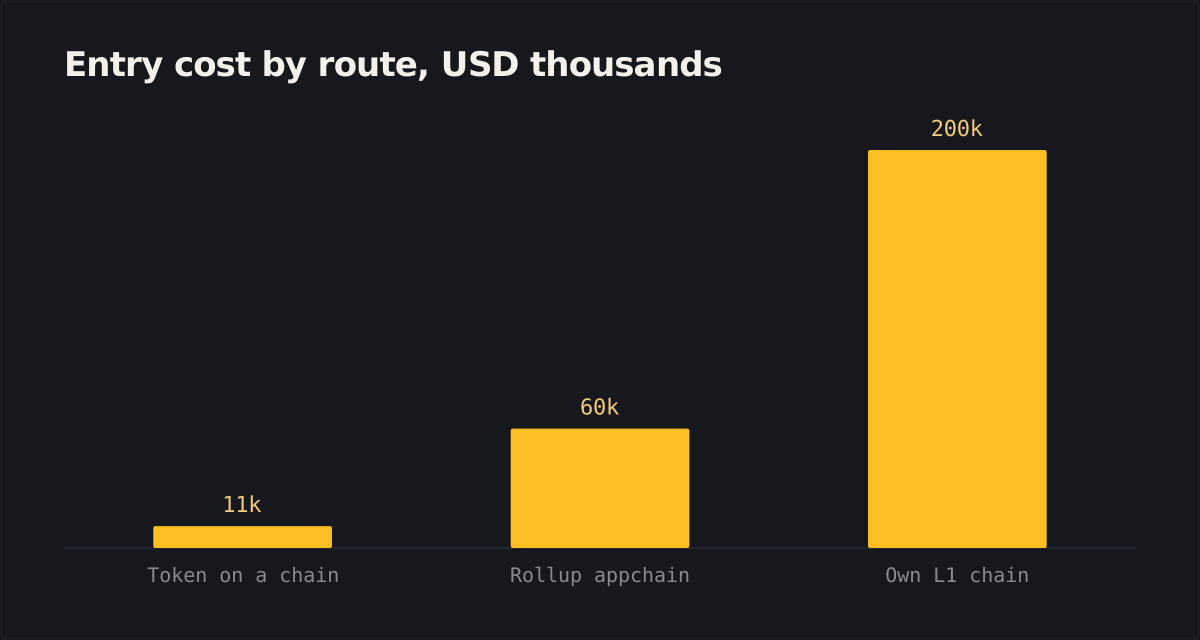
What the cost model assumes
Here is the model in full, with every assumption on the table. Engineer-weeks are 40 hours. The blended rate is $40 to $75 an hour for a senior Eastern European squad, our own planning assumption for this model. Audit prices come from Sherlock's February 2026 market reference, which puts a simple token contract at $5,000 to $20,000, a mid-complexity DeFi protocol at $40,000 to $100,000, enterprise multi-chain systems above $150,000, and each remediation review round at $5,000 to $20,000. Substitute your own rate and the shape holds.
Fair warning about that first row: it assumes the contract really is simple. Add a fee-on-transfer hook, a staking module or an upgrade proxy and you've moved into the middle row's audit bracket without changing chains.
Three things the table deliberately excludes. Legal fees, because they vary by an order of magnitude between a EUR 900,000 exempt offer and a full MiCA white paper with counsel in three jurisdictions. Liquidity, because it's capital you post rather than money you spend. And operations, which is where the appchain and L1 rows overtake everything else inside the first year.
Sherlock's reference also prices two multipliers worth knowing before you scope. Non-EVM languages carry a premium: Rust on Solana runs 25% to 40% above Solidity, Cairo and Move 30% to 45%, and zero-knowledge circuits 80% to 120%. A rushed timeline adds another 20% to 40%. Both are avoidable with a calendar rather than a cheque.
Security and audits before you launch a cryptocurrency
An audit isn't a certificate. It's a time-boxed review of your cryptocurrency's code by people who break contracts for a living, and it's the last point at which a mistake is still cheap. Because a deployed token contract is normally immutable, the audit is also the only meaningful quality gate you get.
Sherlock's pricing note also gives you a planning figure for the calendar, which matters more than the invoice: roughly 3 days of review for 500 nSLOC, 18 days for 3,000, and 38 days for 6,000. Add a remediation round on top. That is why a "six-week launch" is usually a launch with no audit in it, and why the audit is the thing your timeline should be built around rather than squeezed into.
Before the auditors arrive, do the cheap work yourself. Write tests that assert the supply is what you claim it is. Deploy to a testnet and run the full lifecycle, including the vesting release you won't touch for a year. Enumerate every privileged role in the contract and write down, in one sentence each, who holds it and what happens if that key is lost or stolen. If you can't write that sentence, the design isn't finished. Our guides to smart contract audits and blockchain security cover the process and the threat model in detail.
Listing and liquidity: making the token tradable
A cryptocurrency becomes tradable when somebody puts real assets on both sides of a market. On a decentralized exchange (DEX), that's you.
Most DEX pools use a constant product formula, x * y = k, where x and y are the pool's two reserves. As Uniswap's documentation puts it, "larger trades relative to pool depth move the price more (known as price impact), while smaller trades execute closer to the current spot price." That relationship is arithmetic, so you can work out exactly what depth you need before you commit a cent.
How deep a liquidity pool needs to be
Take a $10,000 buy, ignoring fees, against three pool sizes:
Look at the first row. That's what a thin launch feels like from the buyer's seat: a tenth of the pool moves the price by a sixth. Somebody arriving with $10,000 loses $1,667 to the curve on the way in, and the chart they see afterwards isn't a market, it's their own trade. Depth is the difference between a cryptocurrency that trades and one that lurches.
Centralized listings are a separate game and worth being blunt about. Exchanges run diligence on the contract, the team, the distribution and the legal wrapper, and post-MiCA that diligence is heavier in Europe than it was two years ago. Nobody lists a token because it exists. Plan for the DEX pool as the real launch venue and treat a CEX listing, with its own listing fees and exchange economics, as something you might earn later.
What usually goes wrong when people create a cryptocurrency
Token launches fail in a small number of repeatable ways, and every one of them is visible in the contract or the distribution before launch day.
- Admin keys nobody explains. A mint function, a pause switch or an upgradeable proxy controlled by one address. Sometimes necessary, always a liability. If it exists, say so first and put it behind a multisig or a timelock.
- Honeypot patterns, including by accident. A transfer hook, a blocklist or a fee that can be raised after launch means buyers may not be able to sell. Scammers do this deliberately; careless teams do it by copying a template they never read.
- Rug-pull optics without a rug pull. Unlocked team allocations, an unlocked liquidity position, a treasury that moves without explanation. On-chain, honest looks identical to dishonest until you prove otherwise, and the proof has to be a lock, not a promise.
- Decimals. Minting
1_000_000where you meant1_000_000 * 10**18, or the reverse, and it's permanent on an immutable contract. - No demand. This is the most common failure and the least technical one. A token nobody has a reason to hold is a database row with a price feed attached.
Four real cryptocurrency launches and the route each took
Hypotheticals are easy. Here are four real cryptocurrencies and chains, each launched on a different route.
PayPal USD (PYUSD), a token on existing chains. Issued by Paxos Trust Company, N.A. and available on Ethereum and Solana, with reserves and issuance subject to oversight by the Office of the Comptroller of the Currency. A payments company that wanted a token used somebody else's chains and a regulated issuer, and shipped.
USDC, the same route at scale. Circle reports $74.3 billion in circulation as of 7 September 2026, natively issued on 37 blockchains, fully backed by cash and cash equivalents, with monthly reserve attestations by a Big Four firm. Thirty-seven deployments of a token contract, and zero chains of their own.
dYdX Chain, a sovereign appchain. dYdX moved off an Ethereum L2 and onto its own chain because it needed an execution model no shared chain provides. Its documentation describes "an L1 blockchain built on top of CometBFT and using CosmosSDK," with validators keeping the orderbook in memory rather than in consensus. Own the chain when the product requires it, not before.
eStates, a token engine inside a product. We built a real estate tokenization platform for eStates PropTech, an instance of RWA tokenization that split commercial property into on-chain tokens for fractional ownership, alongside the crowdfunding raise flow, the KYC layer and the investor dashboard. The tokens are the smallest part of the system. The product around them is the build.
One pattern runs through all four: every one of them treated the token as a component of a product rather than as the product.
Where to start if you are creating a cryptocurrency
If you're creating a cryptocurrency and you want the shortest honest path: write the distribution table, pick an existing chain, deploy the plainest contract that does the job, budget the audit before the marketing, and post enough liquidity that the first serious buyer doesn't become your price chart. That sequence costs somewhere between $11,000 and $64,000 and takes six to twelve weeks. Everything more expensive than that is a different project wearing the same name.
Then read the regulation for the places your buyers actually live. MiCA Article 4 is a checklist you can work through in an afternoon with counsel, and the SEC's March 2026 interpretation is short enough to read in full. Both are more concrete than the folklore they replaced, which is good news: a rule you can read is easier to comply with than a grey zone you have to guess at. If you want the design reviewed while it's still changeable, send us the distribution table before the constructor is written, not after.
If the token is going into decentralized finance, our explainer on DeFi protocols covers the building blocks you will be composing with, web3 development sets the wider architectural context, and our primer on what cryptocurrency actually is is the right starting point if any of the vocabulary above was new.
Frequently asked questions
You pick one of three routes. Deploy a token contract on a chain that already exists, which is what almost everyone means and what almost everyone should do. Launch your own chain, using a rollup framework like the OP Stack or Arbitrum Orbit or an application-specific chain built with the Cosmos SDK, when your product genuinely needs its own block space. Or use a no-code launcher, which mints something tradable in minutes and gives you no product. The engineering order is the same in every case: decide the supply and distribution first, write and test the contract, get it audited, deploy, then seed liquidity so it can actually be traded.
A coin is the native asset of its own blockchain, so BTC on Bitcoin and ETH on Ethereum. A token is a contract deployed on a chain somebody else already secures, such as an ERC-20 or an SPL token. The gap is not cosmetic: a token rents its security and can be live in weeks, while a coin means you own consensus and validators forever.
Network fees are close to nothing now: Ethereum's average gas price was 0.145 gwei on 10 September 2026 with ETH at $2,468, which puts a deployment in the range of a cup of coffee. The real cost is everything around it. A token on an existing chain, built properly and audited, models out at roughly $11,000 to $64,000. A rollup appchain starts around $60,000. Your own layer-1 starts at a few hundred thousand and never stops, because you are funding validators forever. Liquidity sits outside all of that: it is capital you post, not a fee you pay. Budget for it separately.
Enough to deploy a token contract, nowhere near enough to launch a cryptocurrency. At September 2026 gas prices $100 covers the deployment many times over. It does not cover an audit, a legal opinion, or a pool deep enough to absorb the first real trade. On that budget, build it on a testnet and learn.
Under MiCA, Regulation (EU) 2023/1114, an offer to the public of a crypto-asset that is not an asset-referenced token or an e-money token requires the offeror to be a legal person and to draw up, notify and publish a crypto-asset white paper under Articles 4, 6, 8 and 9. Article 4(2) exempts offers to fewer than 150 persons per Member State, offers whose total consideration stays under EUR 1,000,000 over 12 months, and offers restricted to qualified investors. Article 4(3) puts free distributions and validator rewards outside Title II altogether. This is general information, not legal advice.
As of 17 March 2026 the SEC withdrew its 2019 digital-asset framework and replaced it with an interpretation that sorts crypto assets into digital commodities, digital collectibles, digital tools, GENIUS Act stablecoins and digital securities, with only the last group being securities in itself. The important shift for anyone issuing a token is that a non-security crypto asset becomes subject to an investment contract because of what the issuer promises, not because of what the token is. Your marketing is now the regulated surface. Talk to a securities lawyer before you sell anything.
A template token deploys in an afternoon. A token you would put real money behind takes four to eight engineer-weeks of build, then two to six calendar weeks waiting on an audit and its remediation round, so six to twelve weeks end to end is a realistic plan. A rollup appchain is three to six months before it is worth showing anyone. An independent layer-1 with a real validator set is a year-scale program, and recruiting the validators usually takes longer than writing the code.
Yes, and the result usually is not a product. Token factories deploy a fixed template for you, which is why Base carries 25.8 million token contracts against Ethereum's 2.3 million as of 10 September 2026. You end up with a contract you did not write, cannot change, and cannot explain to an auditor or a listing desk. Fine for an experiment, useless for anything holding customer money.
More from the journal

Blockchain Game Development: Build a Web3 Game Like Pixels
Blockchain game development turns in-game items and currency into player-owned tokens on a blockchain. This guide explains what a blockchain game is, how on-chain ownership works, the web3 tech stack, how a game like Pixels is built, and how to design play-and-earn that lasts.

Smart Contract Development: Lifecycle, Patterns, Cost
Smart contract development is mostly verification, not typing. This guide walks the lifecycle from specification to monitoring, with Solidity code, a language and chain comparison, exploit losses measured from DeFiLlama, and what an audited build costs.

Web3 Development: The 2026 Stack, Costs, and Roadmap
Web3 development swaps the central server for a blockchain, and that one change rewrites the whole stack. Here is the 2026 version: chains, contracts, indexers, wallets, the build sequence, what it costs, and the on-chain data behind each decision.