RWA Tokenization: How Real-World Assets Go On-Chain
RWA tokenization turns a Treasury bill, a loan book, a gold bar or a building into a transferable token. This guide gives the measured size of the market, the legal and standards stack underneath, a comparison of the platforms, and the failure modes nobody advertises.

On this page

RWA tokenization is the issuance of a blockchain token that represents a legal claim on an off-chain asset: a Treasury bill, a fund interest, a loan book, a gold bar, a building. RWA is short for real-world asset. The token is not the asset and never becomes the asset. It's a claim on a legal entity that holds the asset, engineered so that moving the token moves the economic interest behind it.
One clarification before the numbers, because the word collides with an unrelated field. This page is about asset tokenization, also written as real-world asset tokenization. It isn't about data or payment tokenization, the security technique that swaps a card number for a meaningless surrogate. Same word, different discipline. If you want the shortest possible primer first, our explainer on what asset tokenization is covers the basics in two minutes.
The short version
- On 10 September 2026, rwa.xyz measured $39.15 billion of tokenized real-world assets held on public blockchains, excluding stablecoins, across roughly 3.6 million holders. Stablecoins, counted separately, stood at $304.88 billion.
- Tokenized US Treasury funds are the whole story at $15.86 billion. Credit is $7.98 billion, commodities $4.87 billion, stocks $2.91 billion. Tokenized real estate, the use case every article leads with, is $226.54 million across 25 assets.
- Headline market sizes disagree by a factor of ten because they measure different things. The same dashboard also reports $368.37 billion of represented value, and $328.19 billion of that is one repo platform where no investor holds a token in a wallet.
- The legal wrapper does the work. An academic taxonomy of the twenty largest RWA systems concluded that tokens handle representation and transfer while "core legal guarantees remain anchored in off-chain legal wrappers, custodial arrangements, compliance processes, and verification mechanisms".
- ERC-3643 is the only permissioned token standard that reached Final status on the Ethereum standards track. ERC-1400 and ERC-1404 are still Draft and were never merged.
- MiCA doesn't cover tokenized securities at all. Article 2(4) excludes crypto-assets that qualify as financial instruments, which sends a tokenized bond back to MiFID II and the prospectus regime.
- Liquidity is the claim that survives least contact with data. Twelve platforms hold over a billion dollars of tokenized assets each, and a JPMorgan platform holding $903.6 million has nine holders.
What RWA tokenization is
A tokenized asset has two halves that have to stay welded together: an off-chain legal right, and an on-chain token that represents it. Blockchains are good at the second half. They track who holds which token, transfer it in seconds, and settle without a clearing house. They know nothing about the first half. A token doesn't make you the owner of a warehouse. A contract, a title and a court do. The whole discipline consists of keeping those two halves provably in sync.
So the interesting work sits at the seams rather than in the token. Minting is trivial. Making that token an enforceable claim on a specific building, held by a custodian, transferable only to investors who cleared identity checks where the offering is registered, is the actual product.
A June 2026 preprint by Vella, Pennella and Ballandies classified the twenty largest RWA systems across 23 dimensions and reached a conclusion worth quoting, because it's the opposite of how tokenization usually gets sold. Current RWA tokenization, they found, is "predominantly implemented through hybrid architectures", where the chain handles representation, transfer control, redemption workflows and pricing while the legal guarantees stay off-chain. Their taxonomy paper also flags what the industry fails to document across the board: voting rights, dispute forums, burn mechanics, supply constraints and reserve verification, the same tokenomics design questions native crypto tokens face. Those five gaps make a decent shopping list of questions for any issuer.
What is actually tokenized today
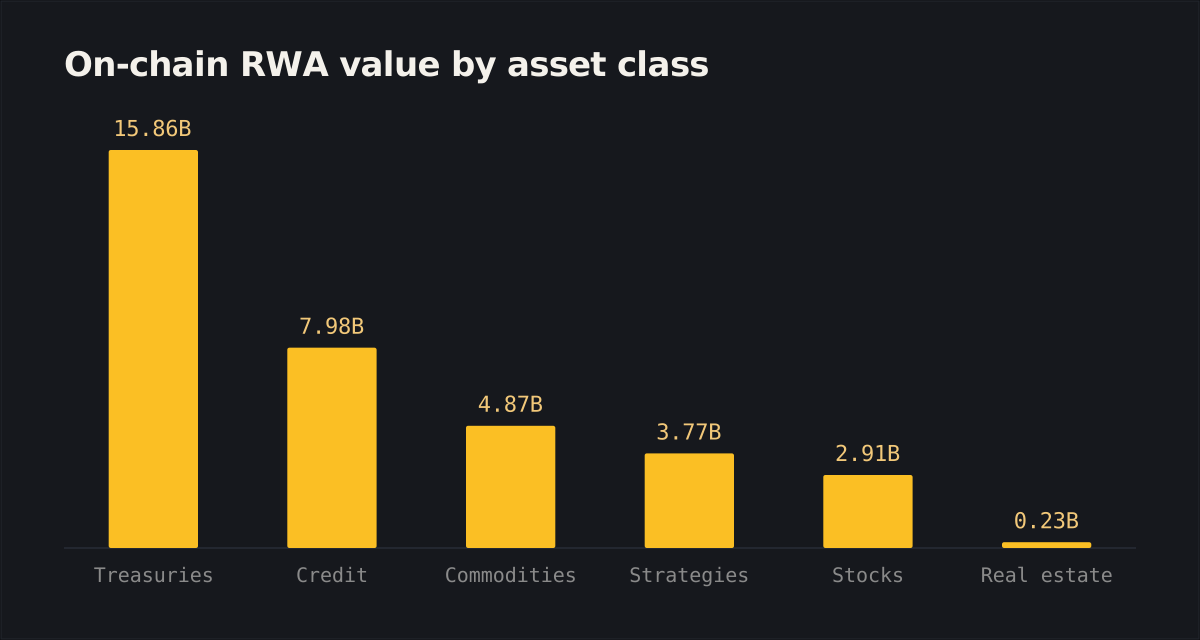
Short-duration government debt is what tokenized. Everything else is a rounding error next to it.
On 10 September 2026, rwa.xyz reported $15.86 billion in tokenized US Treasury funds across 74,253 holders, paying a seven-day APY of 3.45%, the entry point for where tokenised treasuries sit inside DeFi once holders move beyond buy-and-hold. Credit, which the site defines as all non-sovereign debt including private credit and corporate paper, came to $7.98 billion. Commodities were $4.87 billion, almost entirely gold: Tether Gold at $2.65 billion and Paxos Gold at $1.89 billion account for the category between them. Tokenized equities reached $2.91 billion, and that number moves fastest, having added 174% to its holder count in thirty days as brokerages started minting share representations by the thousand.
Then there's real estate, at $226.54 million. Twenty-five assets, 3,032 holders, seven countries, 156 active addresses in the trailing month. Around half a percent of the market, for the use case every explainer opens with. Not for want of trying. A building has no NAV feed, no daily redemption, no existing custodian and no natural buyer on the other side of a trade. A money-market fund has all four before anyone mentions a blockchain.
Source: rwa.xyz asset class pages, captured 10 September 2026.
The pattern isn't subtle. Tokenization works where the off-chain plumbing was already built and blockchain replaces the distribution layer. It stalls where the plumbing has to be invented first.
Why RWA tokenization market sizes disagree
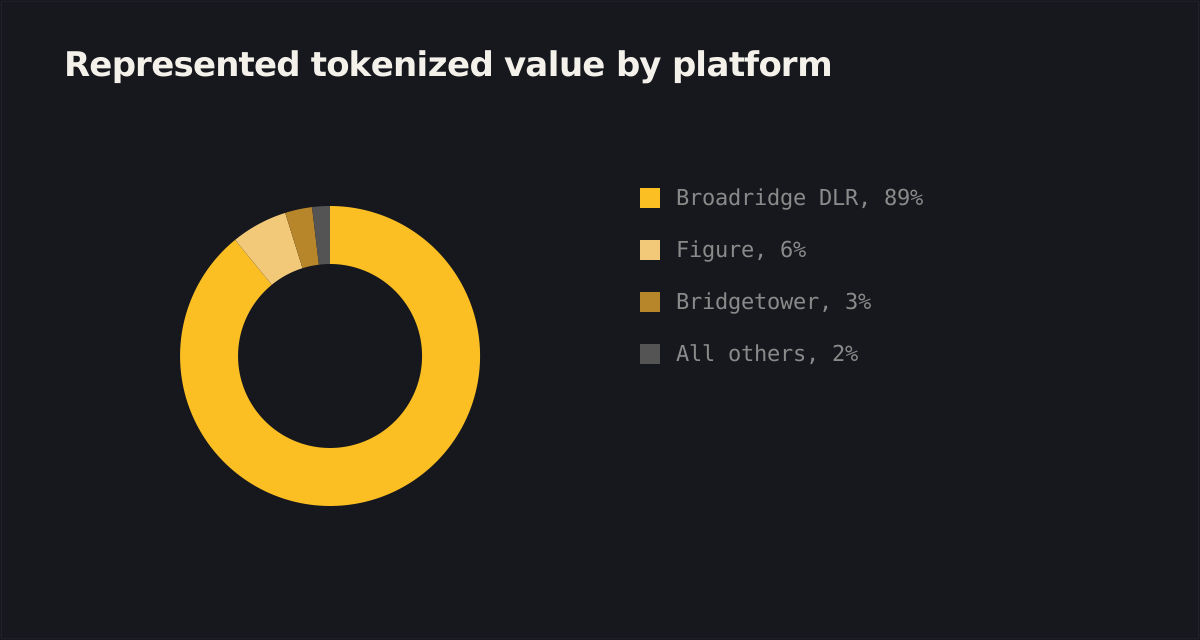
Read four articles on this subject and you'll see four different market sizes, none of which say what was being counted. The denominator is the problem, so it's worth stating once.
The same dashboard publishes two totals side by side. Distributed value, $39.15 billion, counts platforms that use the chain "as a distribution layer, enabling onchain investors to subscribe, hold, and manage assets directly through their own wallets or custodians". Represented value, $368.37 billion, counts platforms using the chain "as a recordkeeping layer, enhancing transparency, reconciliation, and operational efficiency without enabling onchain investor transfer or distribution". Those are the site's own definitions, and the gap between them is nine times the smaller number.
Look at what fills the larger figure. Broadridge's Distributed Ledger Repo platform alone carries $328.19 billion across 8,041 instruments on the Canton network. It's a real production system doing real repo volume, and it's also a back-office ledger between institutions. No retail investor holds a Broadridge repo token in a wallet, and none ever will.
So: quote $39 billion and you're describing tokens people actually hold. Quote $368 billion and you're describing enterprise recordkeeping. Add the $304.88 billion of stablecoins and you can print $700 billion honestly, as long as you say most of it is dollars rather than assets. All three numbers are defensible. Publishing one without its definition isn't.
A second trap: these dashboards revalue continuously. Two captures on 10 September 2026, minutes apart, gave $39.15 billion and $39.12 billion for distributed value, and 3.58 million against 3.89 million holders. Cite a date and treat the second decimal as noise.
How RWA tokenization works end to end
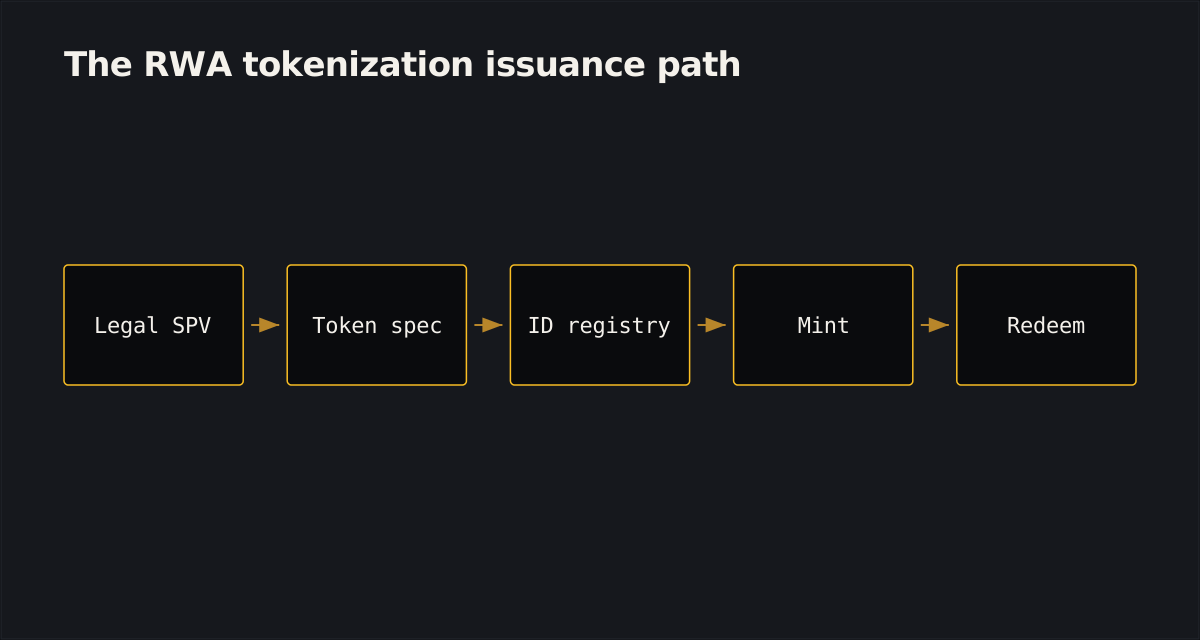
The sequence is the same whether the asset is a tower or a loan portfolio, and most of it happens before anyone writes Solidity.
1. Put the asset in a legal wrapper. An SPV, a trust or a fund holds the asset, and the token is defined as a claim on that entity: a share, a note, a fund interest. That's the step that makes the token mean something a court will recognise. Skip it and you've got a coupon with nothing behind it.
2. Specify the token's rights. What does the holder get: distributions, redemption at NAV, voting, a share of sale proceeds? Under what notice period, and against whom? These answers become contract behaviour, and per the taxonomy paper above, they're the answers most issuers document worst.
- The eligibility layer comes next. An identity registry maps wallet addresses to verified investors and their attributes: jurisdiction, accreditation, lock-up status. The token consults it on every transfer, not only at onboarding, which is the whole reason a permissioned standard exists.
4. Mint to verified holders. Primary issuance runs through the same eligibility check that will govern every later transfer. Ondo's OUSG documentation puts the resulting constraint plainly: the tokens "may be freely transferred between any investors that have already onboarded", and nowhere else.
- Custody, twice. A qualified custodian holds the underlying; key management, whether self-custody, MPC or an institutional vault, secures the tokens. Teams routinely budget for the second and forget the first. Our breakdown of crypto wallet types covers the key-custody options.
6. Feed it a price, and honour redemption. A fund needs a NAV; a commodity needs an attestation. Paxos publishes monthly attestation reports for PAX Gold and describes it as the only gold token redeemable for LBMA Good Delivery bars. Redemption is where a tokenized asset either proves the claim is real or doesn't, which is why the mechanics deserve more scrutiny than the yield.
Secondary trading sits on top of all six. It's the step that fails without anyone noticing, and we come back to it below.
Token standards for RWA tokenization compared
The choice is narrower than vendor decks suggest, and one fact settles most of the argument: only one candidate is a finished standard.
ERC-3643, the T-REX standard, reached Final status on the Ethereum standards track. Its specification defines six interfaces: the token, an identity registry, shared registry storage, a compliance contract, a trusted issuers registry and a claim topics registry. A transfer succeeds only when the sender has an unfrozen balance, both wallets are unfrozen, the receiver is verified in the identity registry, every compliance rule passes and the token isn't paused. Compliance becomes a property of the asset rather than a manual review. Authored by the Tokeny team and recognised as ERC-3643 in September 2021; Tokeny sits in Luxembourg and is now part of Apex Group.
ERC-1400 is a library rather than a single contract, composed of ERC-1410 for partitions, ERC-1594 for transfer checks, ERC-1643 for documents and ERC-1644 for controller operations such as forced transfers. It's been Draft since September 2018, and its proposal issue was closed without ever being merged. Production deployments exist anyway.
ERC-1404 is the minimal option: two functions, detectTransferRestriction and messageForTransferRestriction, returning a numeric reason code and a human-readable explanation. Also Draft, also from 2018, also unmerged, and useful when a venue rather than the token is doing the eligibility work.
A plain ERC-20 with an issuer-controlled allowlist isn't automatically wrong, whatever a standards purist tells you. For a single-jurisdiction offering with one regulated venue and a small holder set, it's less code to audit, and less code means fewer places to be wrong. What it can't do is carry its rules with it when the token turns up somewhere the issuer didn't anticipate.
Polymesh goes the other way, moving identity, compliance, confidentiality, settlement and governance into the base layer of a public permissioned chain. Every participant in an asset transaction has a verified on-chain identity by construction.
Whichever you choose, the contracts move regulated value and usually can't be patched in place. That puts an external review in the critical path, and our guide to the smart contract audit process covers what a serious one looks like.
Tokenization platforms compared
An RWA tokenization platform is a compliance and servicing stack that happens to settle on a blockchain. One caveat before the table: comparison lists routinely mix issuers who distribute tokens to holders with software vendors who sell those issuers the machinery. Different businesses, and only the first shows up in on-chain data.
Source: rwa.xyz tokenization platforms table, captured 10 September 2026; regulatory descriptions from each provider's own filings and documentation.
Two things in that table matter more than the ranking.
One is how much of the licensing stack a single company can hold. Securitize's Q2 2026 results, filed with the SEC in August 2026, list Securitize Markets LLC as a registered broker-dealer running an ATS, Securitize Transfer Agent LLC as a registered transfer agent, Securitize Capital LLC as a registered investment adviser and Securitize Fund Services LLC as the administrator, servicing 663 active funds with $24.3 billion under administration. Tokenized AUM was $4.3 billion at 30 June 2026 on $14.4 million of quarterly revenue. Clients include Apollo, BlackRock, BNY, Hamilton Lane, KKR and VanEck. No other name in the table publishes that full set of registrations.
The other is the holder column, which nobody prints next to the dollar figure and which changes what that figure means. Ondo has 457,382 holders on $3.60 billion. Securitize has 1,871 on $5.01 billion. Further down the same table, STOKR carries $1.52 billion across 62 holders, JPMorgan's Kinexys $903.6 million across 9, and a corporate credit platform called Realiz shows one holder against $500 million. None of those are broken products. They're private placements that happen to settle on a chain, which is a fine thing to be and a different thing from a liquid market.
RWA tokenization regulation by jurisdiction
Tokenization doesn't create a new regulatory category. It inherits the one that already covered the asset, and four jurisdictions have taken visibly different routes to saying so.
European Union: MiCA does not cover tokenized securities
The most common mistake in EU tokenization coverage is assuming MiCA applies. It doesn't. Regulation (EU) 2023/1114, Article 2(4), states that the regulation "does not apply to crypto-assets that qualify as one or more of the following: (a) financial instruments". A tokenized bond, share or fund unit is a financial instrument, so it falls under MiFID II, the Prospectus Regulation and CSDR, exactly as its paper equivalent does.
What MiCA leaves out, the DLT Pilot Regime partly fills. Regulation (EU) 2022/858 has applied since 23 March 2023 and lets a DLT market infrastructure operate with targeted exemptions, inside hard caps: shares only where the issuer's market capitalisation is under EUR 500 million, bonds only under EUR 1 billion of issue size, fund units only under EUR 500 million of assets, and no more than EUR 6 billion of aggregate market value on any one infrastructure. Cross EUR 9 billion and the operator has to begin a transition strategy. The caps are the point. This is a sandbox with a ceiling, not a licence to rebuild a market.
United States: still securities
The SEC's position has been consistent and is stated most memorably in Commissioner Hester Peirce's July 2025 statement, Enchanting, but Not Magical: tokenized securities are still securities. The statement also draws the distinction that most tokenized-equity products depend on. An issuer tokenizing its own shares is one thing. An unaffiliated third party holding securities and issuing a token against them is another, and that token may be a receipt for a security, which is itself a security, distinct from the one held by the distributor, with counterparty risk attached.
Market plumbing has moved since. In December 2025 the Division of Trading and Markets issued a no-action letter covering DTC's voluntary securities tokenization program, limited to transfers between registered wallets of DTC participants, with DTC's own system remaining the official record. Peirce called it an incremental step, and it is. It's also the incumbent settlement layer conceding that chain-native records are worth piloting.
Switzerland: the token is the security
Switzerland went furthest and changed private law rather than issuing guidance. The Federal Act of 25 September 2020 on the Adaptation of Federal Law to Developments in Distributed Ledger Technology, in force since 1 February 2021, inserted Article 973d into the Code of Obligations and created the ledger-based security: a right that is registered in a securities ledger and "may be exercised and transferred to others only via this securities ledger".
The ledger has to meet four conditions. It must give creditors, but not the obligor, power of disposal over their rights. Its integrity must be protected against unauthorised modification, "such as joint management by several independent participants". The content of the rights and the registration agreement must be recorded in the ledger or in linked data. And creditors must be able to verify the ledger contents relating to themselves without a third party. Article 973e then protects a good-faith acquirer even where the seller wasn't entitled to dispose. That's the difference between a token that points at a security and a token that is one.
Singapore and the UAE: RWA tokenization sandboxes
Singapore runs Guardian, a cross-border MAS sandbox that has produced live use cases with Ant Group, Apollo, DBS, Franklin Templeton, Hamilton Lane, OCBC and UBS, plus published output including the Guardian Fixed Income Framework and an operational guide for tokenised funds. There's a grant scheme for digital bond issuance too.
In Dubai, VARA regulates virtual assets across the emirate's free zones and mainland, excluding the DIFC, under the Virtual Assets and Related Activities Regulations 2023. Same caveat as everywhere: where a token is a security, the securities regulator has the last word, and the boundary sits in a different place in each of these jurisdictions.
What's still unsettled everywhere: who may operate a secondary venue for tokenized securities, when settlement is legally final on a public chain, whether a foreign holder's transfer restrictions are enforceable in the holder's own courts, and what happens to the tokens if the issuer of the wrapper goes insolvent. Nobody has clean answers. Treat any vendor who says otherwise as a marketing problem.
How to build or choose a tokenization platform
Three routes into RWA tokenization, and the choice is mostly about who carries the licences.
Issue on someone else's platform. You bring the asset and the legal wrapper; Securitize, Centrifuge or a similar issuer brings the transfer agency, the eligibility checks and the distribution. Fastest to market, least control, and you inherit their chain and venue decisions. This is the right answer for most first issuances and almost all funds.
White-label the software. Tokeny, DigiShares and their peers sell the issuance machinery, and you run the offering under your own licences and your own legal opinions. You get control of the product surface and none of the regulatory shelter. Sensible when you plan repeat issuance in one jurisdiction.
Build the platform. Justified when the product is the platform rather than a single asset: a marketplace, a lending venue, an issuer serving many sponsors. Here the smart contract is genuinely the smallest line item.
That last point is the one buyers get wrong. Cost sits in the parts that recur: fund or SPV formation and a legal opinion per offering, transfer agency and fund administration, custody, a KYC and AML vendor, periodic attestation or audit of the underlying, and an external contract audit before every material upgrade. Securitize's own numbers make the ratio concrete. In Q2 2026 it earned $7.8 million from tokenization and $6.6 million from asset servicing. Running the machine costs about what building it did, forever.
We've been on the build side of this. Idealogic designed and built e-States, a real estate tokenization platform for commercial property, across five engagements over six to eight months: a token engine that splits a property's value into on-chain units, a crowdfunding raise flow with KYC and AML onboarding inside the same path an investor uses to commit, an investor dashboard where the raise, the holding and the property's performance meet, and blockchain anchoring so the ownership record is checkable rather than asserted. The architecture is deliberately hybrid, with ownership and transfer rules on-chain and property documents off it. We build to the controls a regulated offering needs; the client runs the offering and its compliance. That split isn't a disclaimer, it's the shape of every honest engagement in this space.
Before any of it, decide whether you need a chain at all. If your product is an operator-run register with a fixed investor set and no secondary market, you're describing a database with extra steps. Our piece on enterprise blockchain works through that decision without the enthusiasm, and web3 development covers the wider stack once you've made it.
Where RWA tokenization goes wrong
Four failure modes, in rough order of how late you find out about them.
The claim isn't enforceable where it matters. A token issued under one jurisdiction's exemption, held by someone in another, restricted by rules encoded in a contract that no court in the holder's country has considered. The transfer restriction works perfectly on-chain. Whether it survives a dispute off-chain is untested for most structures, and it's the risk that never shows up in a dashboard.
The price feed is the product. A tokenized fund is only as honest as its NAV, and a tokenized commodity only as honest as its attestation. Where the underlying is illiquid, the mark is a judgement made by a party with an interest in the answer. Paxos publishing monthly attestations and offering physical redemption sits at the high end of this. Ask for the equivalent from anyone tokenizing something that doesn't trade.
Liquidity that was never there. This is the one that sells tokenization and the one the data contradicts hardest. Tokenized real estate turned over through 156 active addresses in a month. Kinexys has nine holders. Realiz has one. Fractionalising an asset creates the possibility of a secondary market. It doesn't create buyers, and a token with no bid is less liquid than a fund share with a redemption window, not more.
Then there's concentration in the boring layer. Custody, the transfer agent and the issuer of the wrapper are single points of failure that no amount of decentralisation at the token layer touches. The same shape of problem shows up in DeFi, where the damage is often operational rather than a contract bug; our overview of blockchain security and our taxonomy of DeFi protocols both walk through how that plays out.
If your mental model is that tokenization removes intermediaries, correct it now. It relocates them. The custodian, the administrator and the transfer agent are all still there, and you've added a smart contract plus a key-management problem on top. What you gain is settlement speed, eligibility you can program, and a register nobody can quietly edit. Real gains, none of them disintermediation. The difference between issuing an RWA token and creating a cryptocurrency is mostly the paperwork that makes the first one enforceable.
A checklist for evaluating a tokenization platform
Ten questions. A vendor who can't answer them in writing has answered them.
- What legal entity holds the asset, in which jurisdiction, and what exactly does one token entitle its holder to?
- Under which exemption or registration is the offering made, and who wrote the legal opinion?
- Which token standard, and if the answer is a custom contract, why?
- Who is the transfer agent or its functional equivalent, and is the on-chain register the official one or a mirror?
- Who custodies the underlying, and who custodies the keys? Two answers, not one.
- How is the price or NAV produced, how often, and by whom?
- What is the redemption path, what is the notice period, and what happens if the queue is longer than the cash?
- Who can block or force a transfer, under what conditions, and is that power on-chain or contractual?
- How many holders does the asset actually have, and what was last month's transfer volume?
- Which auditor reviewed the contracts, when, and is the report public?
Questions 7 and 9 separate a working product from a nicely rendered one.
What RWA tokenization is good for right now
RWA tokenization was never a question of whether a blockchain can represent a building. It obviously can. The question is whether the legal wrapper, the custody arrangement and the compliance logic are sound enough that the token is a claim somebody can enforce, and whether anyone is on the other side when a holder wants out.
The measured answer, on 10 September 2026, is that it works beautifully for assets that already had daily pricing, regulated custody and a transfer agent. That's why $15.86 billion of it is Treasury funds and $226.54 million is real estate. In the first category the path is well trodden and the platforms are real. In the second, budget for the plumbing you're about to invent, and be honest with investors about the secondary market that won't exist for a while.
That's the work our blockchain development team does on tokenization engagements: specify the rights before the Solidity, build on standards that already went through review, wire identity, custody and eligibility into the transfer path, and ship behind an external audit. Worth meeting that bar before issuance rather than after.
CEO and Co-founder at Idealogic. Leading software strategy, systems architecture, and AI-native engineering squads since 2016.
Frequently asked questions
RWA tokenization is the issuance of a blockchain token that represents a legal claim on an off-chain asset: a Treasury bill, a fund interest, a loan book, a gold bar, a building. RWA stands for real-world asset. The token isn't the asset. It's a claim on a legal entity that holds the asset, built so that transferring the token transfers the economic interest. Excluding stablecoins, rwa.xyz measured 39.15 billion dollars of such tokens held on public chains on 10 September 2026.
Technically yes, commercially almost never. You can't tokenize the deed itself in most jurisdictions, so the house goes into an SPV or trust and the tokens represent equity in that entity, which is usually a security. That means a legal opinion, a filing or an exemption, investor eligibility checks and a transfer agent, then ongoing valuation and reporting for as long as the tokens exist. For one residential property the fixed costs swamp the asset. Tokenized real estate stood at 226.54 million dollars on rwa.xyz on 10 September 2026 across 25 assets, moving through 156 active addresses a month, so there's no waiting secondary market either.
Asset-backed token is the broader, looser phrase: any token whose value is meant to come from something held in reserve, including fiat-backed stablecoins. RWA tokenization describes a specific construction, where a named off-chain asset sits in a legal wrapper and the token is an enforceable claim on that wrapper, with issuance and transfer gated by securities rules. Every RWA token is asset-backed. Plenty of asset-backed tokens aren't RWAs, because nothing about the reserve is legally enforceable by the holder.
By value held on-chain on rwa.xyz on 10 September 2026: BlackRock's BUIDL at 2.75 billion dollars, Tether Gold at 2.65 billion, Circle's USYC at 2.60 billion and Ondo's USDY at 2.20 billion. Three of the four are short-term US government debt, which is where RWA tokenization actually landed. Size measures distribution rather than quality, and none of this is a recommendation to buy anything.
By value distributed to on-chain holders on rwa.xyz on 10 September 2026: Securitize at 5.01 billion dollars, Ondo at 3.60 billion, Franklin Templeton's Benji at 2.48 billion, Paxos at 1.89 billion, Centrifuge at 1.55 billion and Maple at 1.02 billion. Software vendors that don't issue anything themselves, Tokeny and DigiShares among them, never appear in rankings like this, which is why no two lists agree.
ERC-3643, the T-REX standard, is the only one of the permissioned candidates that reached Final status on the Ethereum standards track, in 2021. It puts an identity registry and a compliance module in the transfer path, so a transfer reverts unless both parties hold the required claims. ERC-1400 and ERC-1404 are still Draft and were never merged into the EIPs repository, though implementations of both are in production. A plain ERC-20 with an issuer-controlled allowlist is defensible for a single-jurisdiction offering where the venue does the eligibility work.
There's no honest single number, because the smart contract is the cheap part. The bill is dominated by things that recur: SPV or fund formation and a legal opinion per offering, transfer agent and fund administration, a custodian, a KYC and AML vendor, periodic attestation or audit of the underlying, and an external smart contract audit before issuance. Securitize, the largest issuer by on-chain value, reported 7.8 million dollars of tokenization revenue against 6.6 million of asset servicing revenue in the second quarter of 2026. That ratio is the honest answer: running the thing costs about what issuing it did.
Yes, by the rules that already covered the underlying asset. In the EU, MiCA explicitly doesn't apply to crypto-assets that qualify as financial instruments, so a tokenized bond falls under MiFID II and the prospectus regime instead. In the US, the SEC's position is that tokenized securities are still securities. Switzerland went further and amended its Code of Obligations so a ledger-based security can exist as the security itself. What's unsettled is market structure: who may operate a venue, how settlement finality works, and how a chain-native register interacts with an incumbent one.
More from the journal

How to Read a Cryptocurrency Market Forecast in 2026
A cryptocurrency market forecast is a set of scenarios, not a prediction you can bank on. This guide explains the forces that move the crypto market, from halving cycles and interest rates to ETFs, regulation, and stablecoins, and how to read any outlook without gambling.

Tokenomics: How to Design a Token Economy That Holds Up
Tokenomics is the design of a token's supply, distribution, vesting and demand. This is a founder's guide to designing one: the components, benchmark allocations from 150+ launches, dated examples from Ethereum to Terra, and a step by step method.

Real Estate Tokenization: How It Works, Step by Step
Real estate tokenization converts property into on-chain tokens via an SPV, enabling fractional investing with lower minimum tickets. How the legal wrapper, token contracts, KYC, primary raise, distributions, and secondary market work, and where the limits are.