Real Estate Transaction Management Software: The Build
Real estate transaction management software runs the deal from offer to close. Here is the transaction data model, why e-signatures are legally binding, how the compliance audit trail and critical-dates engine work, how commission splits compute, and when to build.

Real estate transaction management software is, underneath the checklists, the system of record for a deal between the day an offer is accepted and the day it closes. It holds who the parties are, which documents they signed and when, the disclosures and tasks the file needs to be compliant, the critical dates that can kill the deal if they slip, and the commission that pays everyone at the end. When it works, the agent, the broker, and the coordinator read the same file, every deadline has a reminder, and the closed transaction survives a real estate board audit. When it does not, a contingency lapses unnoticed, a disclosure is missing from the file, and a deal or a license is at risk.
This article is the build guide for that system, not a vendor shortlist. It leads with the part the category pages skip: the transaction data model, then why an e-signature is actually binding, the compliance audit trail as engineering, the critical-dates engine, and how commission splits compute. The focus is the lifecycle from offer to close. The post-close operation, leases and maintenance and tenants, belongs to property management software; the trust ledger and the disbursement belong to real estate accounting software; the commercial lease after signing belongs to commercial real estate software. This is the deal that gets a property to close.
The short version
- Real estate transaction management software is the system of record for a deal from accepted offer to close, holding the parties, documents, tasks, critical dates, and commission, and agents, transaction coordinators, and the legally responsible broker all work from the same file.
- The foundation is the data model: a transaction is a graph of parties, documents, tasks, deadlines, and a commission rather than a folder of PDFs, and getting it right turns the checklist, the reminders, and the commission math into queries.
- E-signatures are legally binding on real estate contracts under the US ESIGN Act and UETA and the EU eIDAS regulation once consent and intent are captured, and the same append-only audit trail of who signed what and when is what lets a file survive a state real estate board audit.
- The critical-dates engine models the deal as a chain of dependent dates offset from an anchor and counted in business days, so moving the closing cascades every downstream contingency and no deadline lapses silently.
- Commission is a calculation with a sequence, not one percentage: the gross fee splits between the listing and selling sides, then each side applies the brokerage's splits, caps, team splits, and referral fees, while booking the money stays with accounting software.
- Buy or configure a packaged tool such as Dotloop, SkySlope, or Brokermint when your workflow matches the market norm, and build custom when your commission logic, multi-state compliance, white-label, or integrations are the differentiator; many brokerages run a hybrid.
What real estate transaction management software is, and who uses it
Real estate transaction management software is the workspace a brokerage uses to run a deal from accepted offer to close: the parties and their roles, the documents and signatures, the disclosures and tasks, the deadlines, and the commission. It is used by agents, by the transaction coordinators who shepherd files for a team or office, and by brokers who are legally on the hook for every file the office produces.
The question it answers is often phrased as software versus a transaction coordinator, and that framing misses the point. A transaction coordinator is a person who does skilled work: chasing a missing signature, confirming an inspection happened, assembling a file a compliance reviewer will accept. The software does not replace that judgment; it removes the mechanical load around it. It turns the checklist into a tracked workflow, the deadlines into reminders that escalate, and the file into an organized, auditable record. The result is leverage. One coordinator can carry many more deals without a contingency slipping, and a broker gets consistency across an office instead of a different filing habit per agent.
The data model behind real estate transaction management software
The hardest and most underrated part of real estate transaction management software is the data model, because a deal is not a folder of PDFs; it is a set of related objects that the documents, dates, and money all hang from. Get the model right and the checklist, the reminders, and the commission math become queries against it. Get it wrong and every workflow fights the structure, and the compliance file is something a person reassembles by hand at closing.
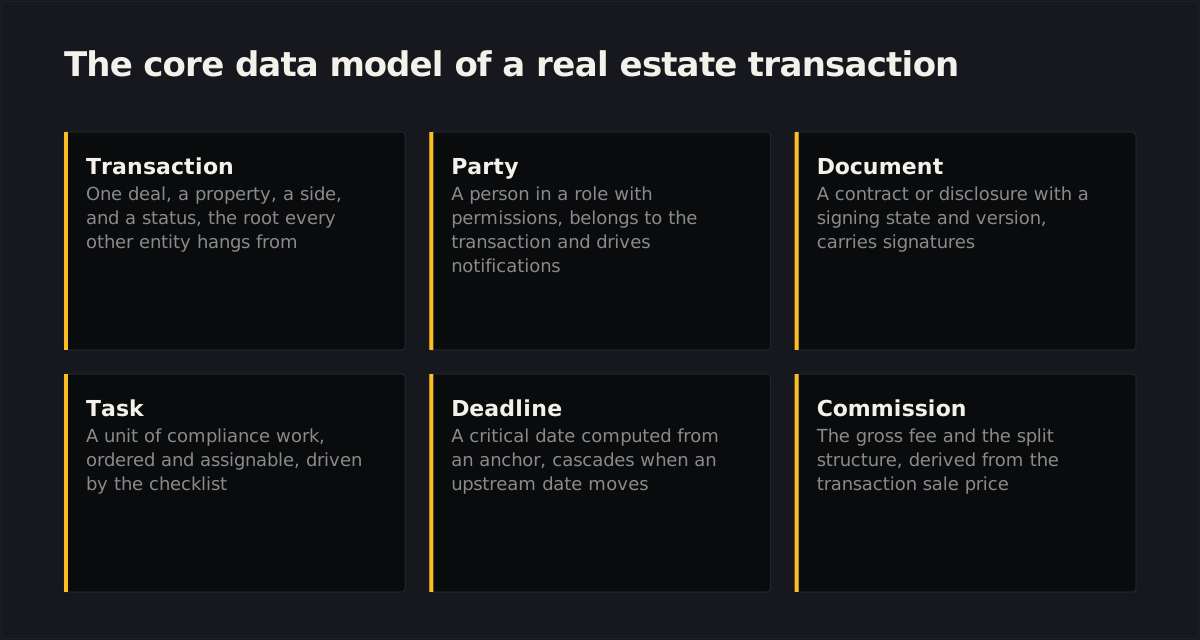
Start with the transaction itself: one deal, anchored to a property and a side, listing or buying, carrying a status from accepted to closed. Hanging off it are the parties, the buyer, seller, both agents, the lender, the title or escrow officer, the coordinator, each a role rather than a name so permissions and notifications follow the role. Then the documents, the purchase agreement, disclosures, addenda, each with a signing state and a version. Then the tasks, the things the file needs done, ordered and assignable, often driven by a compliance checklist. Then the deadlines, the critical dates that govern the deal, which the next sections treat as their own engine. And the commission, the money the closed deal produces and how it divides. The figure below sets out the core entities, what each holds, and the relationship that ties it to the rest.
Document workflow and e-signature legality
Documents are the visible product of a transaction, and the single feature buyers ask about first is the electronic signature, so it is worth being precise about why an e-signed contract actually holds. The workflow itself is a state machine: a document is drafted, sent for signature, partially signed, fully executed, and filed, and the platform tracks each transition and who caused it. The legality sits underneath that.
In the United States, the governing law is the federal ESIGN Act, which establishes that an electronic signature and an electronic record have the same legal effect as a handwritten signature and paper, so an e-signed purchase agreement is enforceable. UETA is the state-level parallel that most states adopted to the same end. ESIGN attaches real conditions a build has to honor. For consumer transactions, the signer must affirmatively consent to transact electronically and be able to access the records, and the platform has to capture that consent. And a set of documents are carved out, wills and certain notices among them, so the system cannot assume every paper can go electronic.
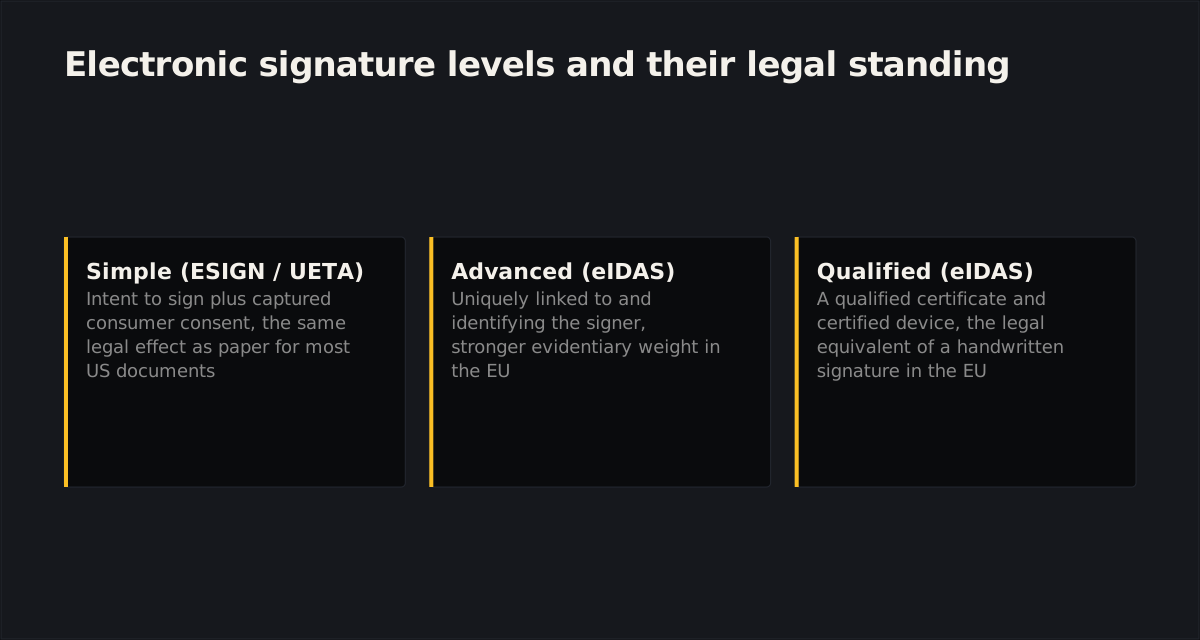
The EU draws the line differently. The eIDAS Regulation recognizes three signature levels: a simple electronic signature, an advanced electronic signature tied to and capable of identifying the signer, and a qualified electronic signature created with a certified device and a qualified certificate. Only the qualified signature carries, by regulation, the legal equivalent of a handwritten one. The level a transaction needs depends on the document and the jurisdiction, which is exactly why a serious platform models the signature level as data rather than treating every signature the same. Idealogic built a qualified e-signature platform with identity verification and a tamper-evident audit trail, which is the engineering shape this requires. The figure below maps the three levels to what each demands and the standing it carries.
How real estate transaction management software handles compliance
Compliance is where real estate transaction management software earns its keep for the broker, because the broker, not the agent, answers to the state real estate board when a file is incomplete or a signature is disputed. The product the software has to produce is a file that survives an audit, and that is an engineering problem about evidence, not a folder of documents.
The core of it is an immutable audit trail: an append-only event log that records every meaningful action on the transaction, who did it, to which object, and exactly when. A document was sent at this timestamp, viewed by this party, signed from this place, a disclosure was acknowledged, a task was completed and by whom. The discipline is that events are never edited or deleted, only added, so the history is complete and a later dispute traces to the recorded fact rather than someone's memory. That is also what backs the certificate of completion an e-signature should produce, the who-signed-what-and-when summary attached to the executed document. On top of the log sits the compliance checklist, the required documents and disclosures for this deal type and state, with the file gated so a transaction cannot be marked complete while a required item is missing. Done well, an audit is a query against the event log, not a frantic reconstruction the week a board examiner calls.
The critical-dates and contingency engine
If documents are the visible product, the critical-dates engine is the part that quietly saves deals, because in a purchase contract a missed contingency deadline can forfeit a buyer's earnest money or hand a party the right to walk. The engine models the deal as a chain of dependent dates rather than a flat list of reminders, which is the difference between software that tracks dates and software that protects them.
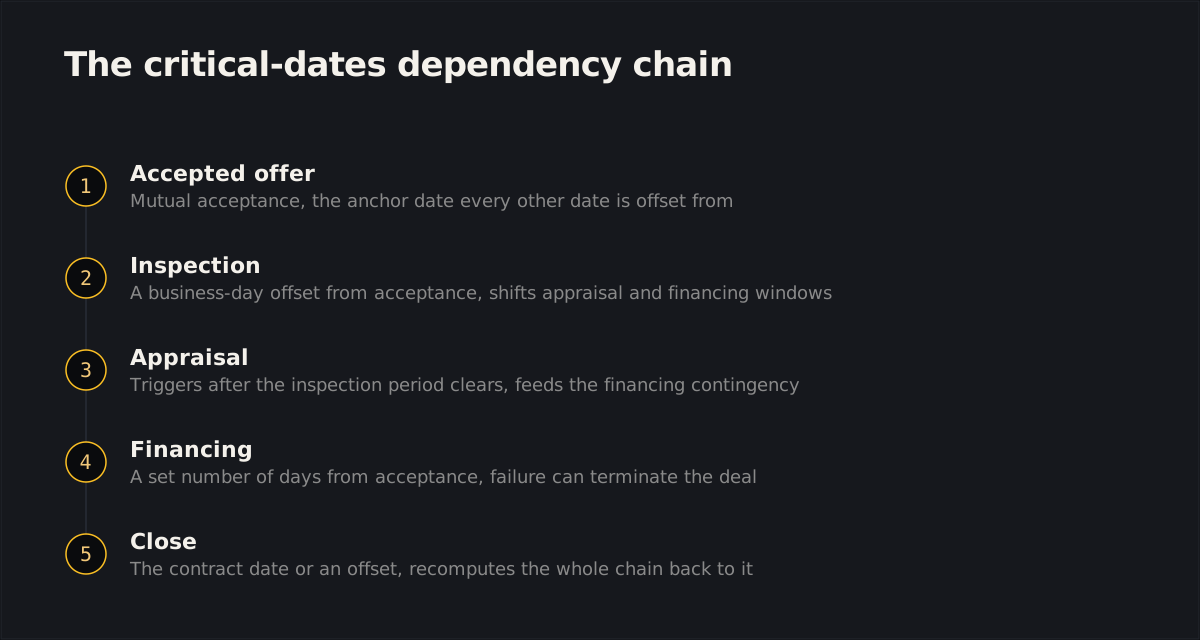
The chain has an anchor, usually the accepted-offer or mutual-acceptance date, and each milestone is defined as an offset from an anchor: inspection due ten days after acceptance, appraisal ordered after the inspection clears, the financing or loan contingency a set number of days out, the close a fixed date or offset. Two rules make it correct. First, business-day calculation: many contract periods count business days, so the engine skips weekends and holidays rather than counting raw calendar days, and it has to know the right calendar. Second, cascading recalculation: when an upstream date moves, the close is pushed a week, every dependent date downstream recomputes at once, instead of leaving a coordinator to redo the math by hand and miss one. Over the chain sits an escalating reminder schedule so a date approaches loudly, not silently. The figure below traces the dependency chain, what triggers each milestone, and what cascades when it moves.
Commission calculation and splits
Commission is the part of real estate transaction management software that touches money, and the reliable way to think about it is as a calculation with a defined sequence, not a single percentage someone types at the end. The order matters because each step operates on the result of the last, and getting the order wrong pays the wrong person.
The sequence starts with the gross commission, a percentage of the sale price or a flat fee set in the listing agreement. It splits first between the listing and selling sides of the deal. Then, on each side, the brokerage applies its agreement with the agent: a base percentage split, a cap after which the agent keeps all or most of further commission for the year, team splits where a lead agent shares with members, referral fees paid off the top to another broker, and franchise or transaction fees the brokerage deducts. The engine computes each tier in order and shows the net to each party, which is what an agent checks and a broker approves. The boundary to hold is sharp: calculating the split is transaction work, but booking the money, the trust deposit, the disbursement, the ledger entries, is accounting work, and it belongs to real estate accounting software. The transaction platform produces the number and the breakdown; the accounting system posts it. Keeping that line clean is what stops a transaction tool from quietly becoming a half-built ledger.
Closing workflows in real estate transaction management software
Closing is where the file meets the rest of the industry's systems, and it forks hard between residential and commercial, so real estate transaction management software has to model both paths rather than assuming one. Before either, the documents usually originate in a forms library, and the platform integrates with the standard ones, zipForm and Lone Wolf TransactionDesk for association and brokerage forms, and increasingly the RESO data standard and Web API for listing data, so a deal does not start with rekeyed fields.
On the residential path, the closing is governed by the federal TRID rule, the TILA-RESPA integrated disclosure, and its hardest-edged requirement drives the schedule: per the CFPB, the borrower must receive the Closing Disclosure at least three business days before closing. That single rule reaches back into the critical-dates engine, because the disclosure date is a deadline the software has to compute and protect, and a re-disclosure can reset the clock. The commercial path looks different: no consumer TRID disclosure, but a heavier diligence load, title and survey review, escrow conditions, entity and authority checks, and financing contingencies that dwarf a residential loan approval. At that seam a commercial deal hands off to lease administration, which commercial real estate software owns once the property is operating. Modeling closing as two configurable workflows, rather than one residential happy path with commercial bolted on, is what keeps both correct.
Document retention and record-keeping rules
The deal does not end at closing for the broker, because the file has to be kept, intact and unaltered, for years afterward, and record-keeping is a requirement the software should enforce rather than leave to a shared drive. The reason is regulatory: a real estate board can examine a brokerage's files long after a sale, and a missing or altered record is the broker's liability.
The rules are set per jurisdiction. The National Association of Realtors frames retention as keeping the complete transaction file, and each state real estate commission sets the minimum holding period in statute, for example under the Arizona Revised Statutes governing real estate brokers; the period is typically a few years from closing, but the exact term varies by state. The engineering follows three principles. Keep the full file, the contracts, disclosures, addenda, earnest-money receipts, and closing statements, not a subset. Store it so it is tamper-evident, which is the same append-only, audit-trailed discipline the compliance section relies on, so an examiner can trust the record was not edited after the fact. And attach a retention clock to the file, driven by the state rule, so nothing is purged before its term and the system can show, per document, why it is still held. Treating retention as a configurable policy rather than a fixed number is what lets one platform serve brokerages across states.
Build, configure, or buy real estate transaction management software
With the model and the engines laid out, the decision is which parts to buy, configure, or build, and the honest framework starts from one question: where does your brokerage differ from the norm? The parts that look like every other office's deals are the parts a packaged product already models. The parts that make you distinctive are the ones no package fits.
Buying or configuring a packaged product is the right default for the common ground. If your forms, your compliance checklist, and your commission math resemble the market standard, a mature tool gives you years of accumulated workflow and someone else's maintenance, and the discipline is to stay close to standard because every customization is a thing you re-test forever. Products like Dotloop, SkySlope, Brokermint, and Paperless Pipeline model the routine deal well. Building custom wins for the differentiating core: commission and split structures a generic engine cannot express, multi-state compliance rules that a single checklist cannot hold, a white-label experience a brokerage or a proptech company competes on, or a deep integration binding your CRM, forms library, and accounting stack into one transaction record. When the list of "the product almost does this" workarounds becomes the implementation, you are already paying for custom software without owning it.
As a market reference, scope drives the number more than screen count: a focused build that proves one workflow starts modest, while a full platform with a configurable compliance engine, a qualified e-signature flow, and CRM and accounting integrations scales well into six figures, because the compliance and commission logic is where the engineering lives. Many brokerages land on a hybrid: keep a packaged tool for routine deals and build the differentiated layer around it. That is the shape of work we do in our custom software development and product development practices, and on the real estate and proptech platforms we build. Our qualified e-signature platform, real-estate app, and real-estate tokenization platform are custom real-estate builds, not packaged products; for the neighboring pieces, the post-close property management software, the multi-tenant architecture behind a SaaS platform, and what proptech is map the rest of the landscape.
Frequently asked questions
Real estate transaction management software is the system of record that runs a deal from accepted offer to close: the parties, the documents and their signatures, the tasks and disclosures, the critical dates, and the commission. A transaction coordinator is the person who does that work, chasing signatures, tracking deadlines, and assembling the compliant file. The software does not replace the coordinator; it gives them a structured workspace and automates the parts that are mechanical, the reminders, the checklist, the audit trail. A good platform lets one coordinator carry far more deals without dropping a contingency date, and gives the broker a file that survives an audit. The coordinator owns judgment; the software owns memory and consistency.
Yes, in almost all cases. Under the federal ESIGN Act, an electronic signature and an electronic record have the same legal effect as a handwritten signature and paper, so an e-signed purchase agreement is enforceable. UETA is the state-level parallel that most states adopted. ESIGN attaches conditions: for consumer transactions the signer must affirmatively consent to do business electronically and be able to access the records, and a few document types are carved out, such as wills and certain notices. In the EU, eIDAS recognizes three signature levels, and a qualified electronic signature carries the legal equivalent of a handwritten one. Real estate transaction management software has to capture consent and intent, not just an image of a signature.
It depends on the state, and the software should treat the retention period as a configurable rule rather than a single number. The National Association of Realtors recommends keeping complete transaction files, and each state real estate commission sets the minimum holding period in statute. Arizona, for example, requires a broker to retain transaction records for a defined number of years under its real estate statutes, and other states set their own terms, typically a few years from closing or listing expiration. The practical design keeps the full file intact, the contracts, disclosures, earnest-money receipts, and closing statements, stores it so it cannot be quietly altered, and stamps each document with a retention clock so nothing is purged before its state-mandated term ends.
It models the deal as a chain of dependent dates rather than a flat list. The accepted-offer date anchors the chain, and each contingency, inspection, appraisal, financing, and the close, is defined as an offset from an anchor, for example ten days after acceptance. The engine computes each date, skips weekends and holidays where the contract counts business days, and recalculates the whole chain when an upstream date moves, so pushing the closing shifts every dependent deadline at once. On top of the dates sits an escalating reminder schedule for the agent and the parties. The goal is that a contingency never lapses silently, because a missed deadline can forfeit earnest money or kill a deal.
It treats the commission as a calculation with a sequence, not a single percentage. The gross commission comes off the sale price, then it splits between the listing and selling sides, then the brokerage applies its agreement with each agent: a percentage split, a cap after which the agent keeps more, team splits, referral fees paid off the top, and franchise or transaction fees. The software computes each step in order and shows the net to every party. The important boundary is that calculating the split is transaction work, but booking the money, the trust deposit, the disbursement, and the ledger entries, belongs to accounting software. The transaction platform produces the number and hands the posting to the accounting system.
Buy or configure a packaged product when your workflow looks like the market norm a tool such as Dotloop or SkySlope already models: standard forms, common compliance checklists, and ordinary commission math. Build custom when the differentiating logic is yours: unusual commission and split structures, multi-state compliance rules that a generic checklist cannot express, a white-label experience a brokerage competes on, or a deep integration with your CRM, forms library, and accounting stack. Many brokerages run a hybrid, a packaged backbone for routine deals and a custom layer for the parts that make them distinct. Idealogic builds custom transaction and real-estate platforms and the integrations around them, rather than selling a packaged transaction product.
More from the journal

Real Estate Investment Software: Underwriting, Waterfalls
Real estate investment software is an underwriting engine and an investor-management system. Here is how the pro-forma model computes returns, the deal and scenario data model, how the equity waterfall and capital calls work, what the LP portal carries, and when to build.

Real Estate Data Analytics: From Rent Rolls to Decisions
Real estate data analytics starts with a data problem: registry, MLS, and rent-roll records that disagree on addresses, units, and timing. Here's what the key joins are, how analytics maturity progresses, and what a useful portfolio dashboard actually answers.

Real Estate Accounting Software: Ledger, Trust, Tax
Real estate accounting software is the system of record underneath a property operation: the general ledger, the trust accounts, and the filings on top. Here is how the ledger and chart of accounts work, how trust reconciles three ways, and when to build.